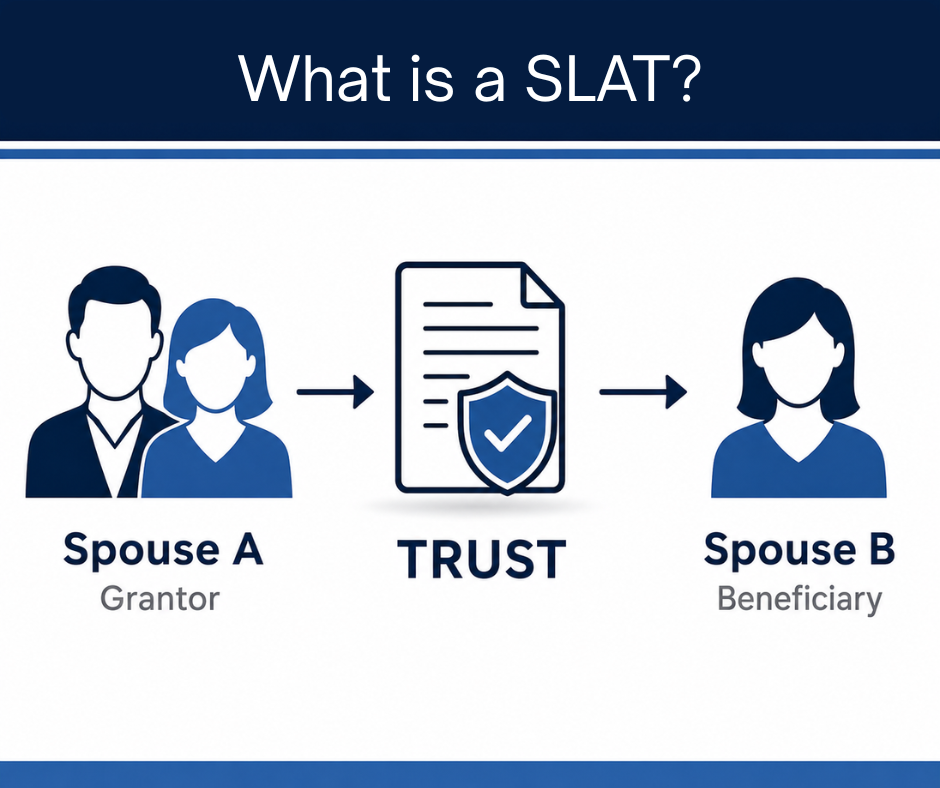
A SLAT, or spousal lifetime access trust, is an irrevocable trust that one spouse creates and funds for the benefit of the other spouse. It moves assets, and their future growth, out of the funding spouse’s taxable estate while the couple keeps indirect access to the money through the beneficiary spouse.
SLATs are a planning tool for married couples with larger estates. This post explains what the term means, how a SLAT works, how the 2026 tax rules affect it, and the risks to weigh before setting one up.
What Does SLAT Mean?
SLAT stands for spousal lifetime access trust. “Spousal” because the trust is for your spouse. “Lifetime access” because your spouse can receive distributions during their life. “Trust” because a trustee holds and manages the assets under written instructions.
The spouse who creates and funds the trust is the grantor. The other spouse is the beneficiary. Children or other family members are usually named to receive what is left after the beneficiary spouse dies.
How Does a SLAT Work?
- The grantor signs the trust. It is irrevocable, so the grantor generally cannot take it back or change the beneficiaries later.
- The grantor funds it with a gift. The transfer is a completed gift that uses part of the grantor’s lifetime gift and estate tax exemption. A gift tax return is usually filed to report it.
- The trustee manages the assets. The trust can hold investments, cash, business interests, life insurance, or other property.
- The beneficiary spouse can receive distributions. The trustee can make distributions to the spouse under the standards in the trust, such as health, education, maintenance, and support. The couple benefits indirectly through the spouse.
- The remaining assets pass on. When the beneficiary spouse dies, the trust continues for, or passes to, the next beneficiaries, usually the children, outside both spouses’ taxable estates.
Key Benefits of a SLAT
Moves future growth out of your estate. Once the gift is made, the assets and everything they earn grow outside the grantor’s taxable estate. For a family with a growing business or investment portfolio, that growth can be the biggest benefit.
Keeps access through your spouse. Unlike most irrevocable trusts, a SLAT lets the couple keep a path to the money while the beneficiary spouse is living.
Uses your exemption while you are alive. In 2026, each person can give or leave up to $15 million free of federal gift and estate tax, or $30 million for a married couple. Amounts above that are generally taxed at up to 40%. The 2025 federal tax law made this higher exemption permanent and indexed for inflation, so the old rush to use it before a 2026 drop is gone. A SLAT still lets you use the exemption now, on assets you expect to grow. Our post on the 2026 federal estate tax exemption explains what changed.
Can protect assets. Assets in a well-drafted irrevocable trust are generally beyond the reach of the grantor’s creditors, and the trust can include spendthrift terms for the beneficiaries. Florida also has a rule written with SLATs in mind. If the beneficiary spouse dies first and the trust then benefits the grantor, the assets are treated as if the spouse had contributed them, not the grantor (Fla. Stat. 736.0505(3)). That helps keep those assets away from the grantor’s creditors. The protection depends on the trust terms and on the transfer not being made to avoid existing creditors.
One point of clarity: Florida has no state estate tax. A SLAT is about the federal estate tax. See Does Florida Have an Estate Tax?
Risks and Limitations to Understand
- You give up control. The trust is irrevocable. The grantor cannot take the assets back.
- Divorce. The beneficiary spouse usually keeps their rights in the trust after a divorce, unless the trust says otherwise. Some trusts define “spouse” as whoever the grantor is married to at the time, which needs careful drafting.
- Your spouse’s death. If the beneficiary spouse dies first, the couple’s indirect access ends, and the assets pass to the next beneficiaries.
- Two SLATs can backfire. If spouses create SLATs for each other with nearly identical terms, the IRS can treat them as if each spouse created a trust for themself, which undoes the tax benefit. This is called the reciprocal trust doctrine.
- No step-up in basis. Assets in a SLAT generally do not get a new tax basis when the grantor dies, so heirs may owe more capital gains tax when they sell.
- Income tax. A SLAT is often set up so the grantor pays the trust’s income tax. That lets the trust grow faster, but it is a real cost to plan for.
- Separate property. The grantor should fund the SLAT with their own property, not property the couple owns jointly.
- Cost and paperwork. A SLAT needs careful drafting, a gift tax return, and ongoing administration.
Who Should Consider a SLAT?
- Married couples whose combined estate is near or above $30 million, or who expect it to grow past that
- Business owners with an interest likely to increase in value
- Couples comfortable giving up direct control of the assets
- Couples in a stable marriage who understand the divorce and death risks
- Families who want to provide for children or grandchildren while keeping access during the spouse’s life
For many Florida families below those levels, a revocable trust and good beneficiary planning may do the job. Our post on joint vs. separate revocable trusts for married couples covers that side.
SLAT vs. Other Trusts
| Trust | Main purpose | Spouse access |
|---|---|---|
| SLAT | Move assets and growth out of the estate while the spouse keeps access | Yes, through distributions |
| Irrevocable life insurance trust (ILIT) | Keep life insurance proceeds out of the estate | Depends on the terms |
| Generation-skipping trust (GST) | Pass wealth to grandchildren and later generations | Usually not the focus |
| Revocable living trust | Avoid probate and manage assets during incapacity | Yes, but no estate tax savings |
The right choice depends on your goals, and some families use more than one. See our post on advanced estate planning strategies.
Frequently Asked Questions
What does SLAT stand for? Spousal lifetime access trust.
What is the definition of a SLAT? An irrevocable trust in which one spouse gives assets for the benefit of the other spouse, usually with children as later beneficiaries.
How is a SLAT different from a regular trust? Most irrevocable trusts cut off the grantor’s household from the money. A SLAT keeps indirect access through the beneficiary spouse. A revocable trust can be changed at any time, but it does not reduce estate tax.
Do I still need a SLAT with a $15 million exemption? Many families do not. A SLAT makes the most sense for couples with estates near or above $30 million, or assets expected to grow a great deal.
What happens to a SLAT in a divorce? Unless the trust says otherwise, the former spouse usually remains the beneficiary. Address this when the trust is drafted, and consider a marital agreement.
What happens if my spouse dies? The couple’s indirect access ends, and the trust continues for, or passes to, the next beneficiaries named in it.
Does a SLAT avoid probate? Yes, for the assets in it. They are owned by the trust, so they pass under its terms, not through probate.
Is a SLAT right for my spouse and me? It depends on the size of your estate, your comfort giving up control, and your goals. Talk with an estate planning attorney before deciding.
Talk With Us About a SLAT
A SLAT can be a strong tool for the right couple and a poor fit for others. SLAT planning is part of SJF Law Group’s high net worth estate planning work for families in Broward, Miami-Dade, and Palm Beach Counties. Contact us to schedule a free consultation.
This post is general information, not legal advice. Every situation is different, and reading it does not create an attorney-client relationship.